Case study – 7orca FX Structuring.
Example involving an institutional real estate manager.
The client’s challenge.
The client, an institutional real estate manager, holds a global real estate portfolio with a significant investment focus on the United Kingdom and was therefore particularly exposed to ongoing GBP/EUR currency risk.
The currency risk was initially managed in-house. In the first phase, the client used a static hedge based on conventional FX forwards. The approach was subsequently changed to GBP put options in order to retain participation in a potential appreciation of the sterling.
Both approaches proved insufficiently viable in the specific mandate’s context. The forward hedge created an ongoing drag on performance due to the negative interest rate differential between GBP and EUR and required significant liquidity when the sterling appreciated. The put option strategy was also costly because of the recurring premiums payments.
Against this background, investors expected the FX Overlay to be entrusted to a specialised, professional manager going forward.
7orca’s solution.
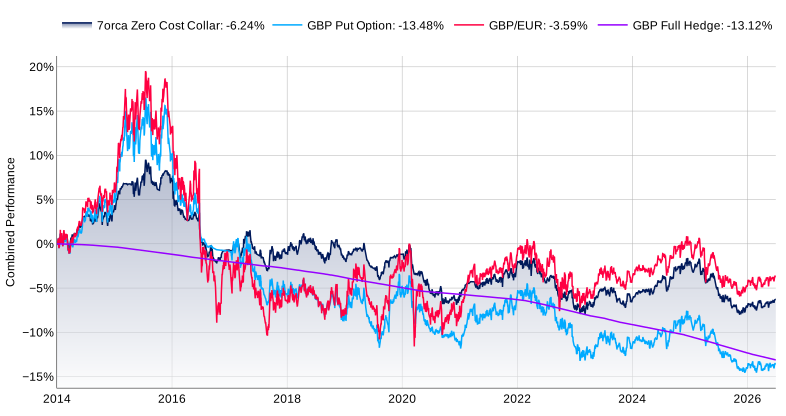
As part of 7orca’s FX Structuring offering, 7orca conducted a structured comparative analysis of the hedging strategies used to date and added a further alternative: a zero-cost collar. This combines the purchase of a GBP put option with the sale of a GBP call option, with the premium received from the call largely or fully offsetting the cost of the put option.
Based on historical data, four alternatives were compared in terms of their impact, advantages and disadvantages and liquidity requirements. Liquidity requirements were also assessed using the GBP stress period of 2014/2015, during which the sterling appreciated by around 15% against the euro.
| Strategie (Wertentwicklung) | Vorteile (+) / Nachteile (–) | Liquiditätsbedarf |
|---|---|---|
| Ungesichert (−3,6 %) | + Kein Aufwand, volle Teilhabe an Aufwertung – Volle Teilhabe an Abwertung – Risiko ungesteuert | Entfällt |
| Forward (−13,1 %) | + Vollschutz vor Abwertung, Kurs fixiert, effizient – Keine Teilhabe an Aufwertung – negative Zinsdifferenz belastet laufend | Einmalige Prämie bei Abschluss (Stresstest: geringster Bedarf) |
| Put-Option (−13,5 %) | + Schutz ab Strike, volle Teilhabe an Aufwertung – Prämie ggf. hoch bei hoher Volatilität | Einmalige Prämie bei Abschluss (Stresstest: geringster Bedarf in Höhe der Optionsprämie) |
| Zero Cost Collar (−6,2 %) | + Definiertes Niveau + kaum Nettoprämie + Teilhabe bis Call-Strike – Restrisiko bis Put-Strike – Aufwertung begrenzt, operativ komplexer | Ggf. Margin aus Short Call (Stresstest: ca. 10 %) |
On this basis, 7orca developed a hedging strategy for the client based on a zero-cost collar that provides a balanced trade-off between hedging effectiveness, costs and liquidity requirements. 7orca provides ongoing support for the strategy across advisory and structuring, implementation and execution as well as monitoring and reporting.
The client's benefit.
The benefit to the client extended beyond the selection of an individual hedging structure. The key was to translate the different hedging approaches into a transparent basis for decision-making that systematically brought together hedging effectiveness, costs, liquidity requirements and operational feasibility.
Significantly more limited and more controllable currency outcomes compared with the approaches previously managed in-house
Significantly lower liquidity requirements during stress periods than under the previous static hedge
A transparent, historically grounded basis for decision-making instead of a predominantly subjective strategy decision
Joint development of a currency hedging strategy tailored to the client in close consultation with a specialised manager
Meeting investors’ requirement for professional and independent management of currency risk
Download the case study – 7orca FX Structuring – as a PDFF FX Management - learn more company - learn more