Case study - 7orca FX Execution.
Implementation of an individual USD hedging structure.
The client's challenge.
At the beginning of 2026, an investor approached 7orca with a specific risk assessment. The investor held US dollar investments of around USD 200m.
Against the backdrop of geopolitical uncertainties and persistent inflationary tendencies, the risk of a depreciation of the US dollar against the euro was to be specifically limited.
At the same time, hedging costs were to be limited while retaining participation in a potential appreciation of the US dollar within a defined corridor.
Specifically, the hedge was intended to take effect once the US dollar had depreciated by 3%. The hedging horizon was six months. Such an asymmetric payoff profile can be represented by an options structure.
In this case, from a USD perspective, a USD put option was envisaged as the protective component. To partially finance the hedging level, the sale of a USD put option further out of the money and the sale of an out-of-the-money USD call option were considered.
The objective was to bring together hedging requirements, hedging costs and upside participation in a consistent structure and subsequently implement it efficiently. In addition, the client expected ongoing valuation of the options structure, reliable settlement and meaningful, clear reporting.
7orca's solution.
Options structure.
Based on the described starting point, 7orca derived the following basic structure for the options strategy.
| Basic structure | |
|---|---|
| Nominal / Exposure | USD 200m |
| Term | 6 months |
| Hedging level | From a 3% depreciation of the US dollar |
| Put-Spread | Purchase of a USD put option 3% out of the money and sale of a USD put option with a lower strike. The aim is to limit downside risk while reducing hedging costs compared with a simple protective put. |
| Short USD call out of the money | Sale of an out-of-the-money USD call option. The aim is to generate premium income to partially finance the hedging costs while limiting further upside participation. |
Some parameters had to be finalised in consultation with the investor. In addition, the costs of the overall structure had to be evaluated. For this purpose, simulations were carried out using different strike levels for the options.
Options strategy
Based on the analysis of different strike constellations and the consultation with the investor, the following options strategy resulted from a USD perspective.
| Options strategy | |
|---|---|
| Long USD put spread | Purchase of a USD put option at 3% OTMF and sale of a USD put option at 6% OTMF. |
| Short USD call | Sale of a USD call option at 5% OTMF. |
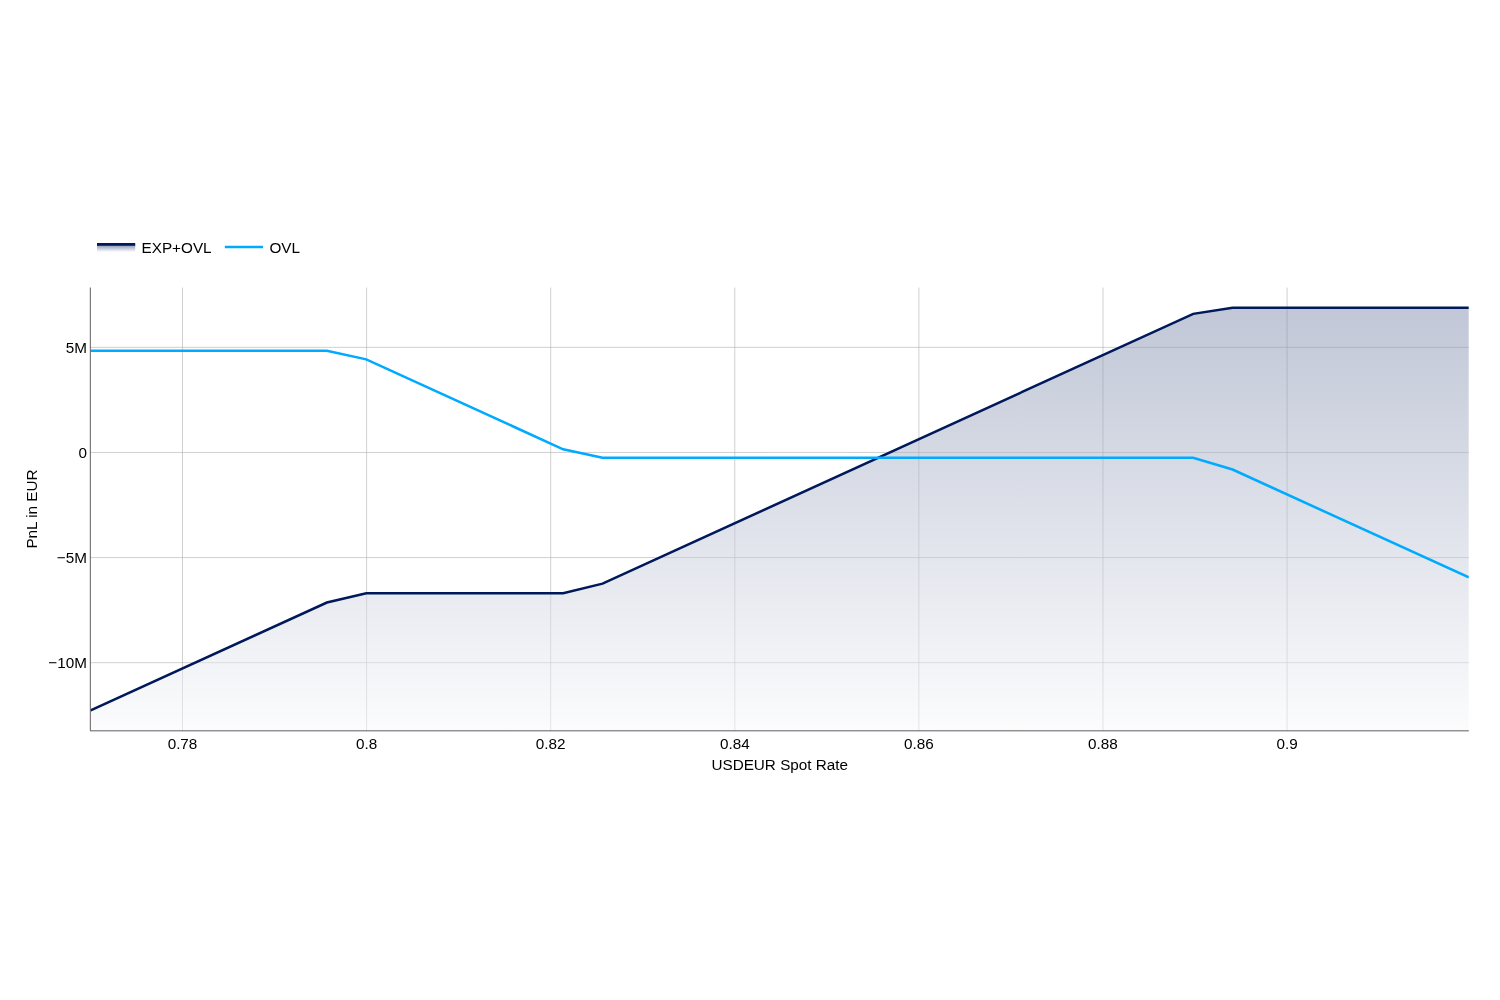
Payoff profile at maturity.
Losses from a depreciation of the US dollar are partially offset between the upper put strike (-3%) and the lower put strike (-6%). Below the lower strike, the hedging effect is limited.
If the US dollar appreciates beyond the call strike, further upside participation is also limited. If the exchange rate at maturity is within the corridor defined by the outer option strikes, the options expire worthless and the investor bears the initially paid net premium.
The amount of the net premium depends on the prevailing market environment. Relevant influencing factors include implied volatility, term, strike distances and interest-rate differentials.
Trade implementation.
For a transaction of this size, efficient trade implementation is central. For FX options, the initial question is whether to use exchange-traded or OTC options. Both routes have distinct advantages and disadvantages.
In this case, connectivity to exchange-traded instruments was already in place. The investor preferred a listed implementation, and the EUR/USD currency pair also shows high liquidity in exchange-traded options.
Even where liquidity is not fully visible in the order book, additional liquidity can be accessed through so-called block trades. In this process, brokers hedge their risk in the OTC market while the investor receives listed options. The US exchange CME has specialised infrastructure in this area. 7orca maintains established contacts with liquidity providers in the field of CME FX Block Trading.
A specific feature of the implementation resulted from the quotation convention of the EUR/USD currency pair. A sold USD call/EUR put structure viewed from a USD perspective is represented in the common EUR/USD quotation as a sold EUR put/USD call option. This conversion applies analogously to the put spread.
As part of the best-execution process, four liquidity providers were approached simultaneously for the overall structure with three option legs. The quotations showed a discernible range. In the documented base case, the strategy was traded at a more favourable level than the previously calculated indicative mid.
The transaction required a net premium of EUR 160,000. The targeted hedging profile was therefore not cost-neutral. However, the premiums from the two sold options reduced the cost of the purchased protective position.
The corresponding parameters are summarised in Table ‘Case study 7orca FX Execution’.
Leg 1 | Leg 2 | Leg 3 | Gesamt | |
| Currency pair | EUR/USD | EUR/USD | EUR/USD | EUR/USD |
| Side | BUY | SELL | SELL | |
| Type | CALL | CALL | PUT | |
| Nominal USD m | 200 | 200 | 200 | 200 |
| Nominal EUR m | 171.116 | 171.116 | 171.116 | 171.116 |
| Expiry | 3 July 2026 | 3 July 2026 | 3 July 2026 | |
| Days to expiry | 177 | 177 | 177 | |
| Strike | 1.2150 | 1.2525 | 1.1225 | |
| Moneyness | 3% OTMF | 6% OTMF | 5% OTMF | |
| Price (EUR) | 0.0049 | 0.0018 | 0.0023 | 0.0008 |
| Delta | 22.66 | 9.23 | -12.74 | 26.17 |
| Impl. vol. | 6.11 | 6.87 | 6.10 | |
| Premium in EUR | -980,000 | 360,000 | 460,000 | -160,000 |
| Premium as % of nominal | -0.5727 | 0.2104 | 0.2688 | -0.0935 |
The client's benefit.
Hedging profile, execution quality and operational control.
The client received a hedging structure individually aligned with its objective. Hedging level, hedging costs and upside participation were transparently weighed against each other and translated into a defined payoff profile.
Before implementation, the structure made the following transparent: the exchange-rate range in which the hedge takes effect; the extent to which it is limited; and the level from which further participation in the US dollar's appreciation is constrained.
The parallel request to four liquidity providers created a robust basis of comparison for executing the overall structure. The implementation therefore included not only the selection and execution of the individual option components, but also the operational integration of the transaction.
Settlement and post-trade processes.
In addition to trading, successful implementation also involved monitoring settlement and correct booking by the administrator. Beyond pure implementation, 7orca assumed further tasks: monitoring margin utilisation and available collateral, ongoing cash management in the segment, preparing regular reporting to value the hedging structure, and maintaining regular technical dialogue with the investor on potential adjustments and the further evaluation of the implemented options strategy.
Requirements for implementation.
For transactions to be implemented by 7orca, the described implementation variant requires 7orca to be mandated as an outsourced manager for the relevant segment. In addition, the required liquidity providers and brokers need to be connected - for exchange-traded derivatives via Give-up Agreements and for OTC derivatives via ISDA master agreements.
7orca maintains an established broker network, meaning that connectivity can generally be prepared in a structured manner. Within FX Execution, 7orca implements the transaction, subject to a corresponding mandate, including the required operational integration. 7orca can additionally provide advisory support, for example in the technical analysis of structure, instrument selection, hedging costs and implementation routes before execution.
As an alternative to the outsourced mandate, 7orca may act within an advisory mandate. In this case, responsibility for execution remains with the executing party.
Download the case study – 7orca FX Execution – as a PDF FX Management - learn more Company - learn more